4:15pm: Stocks rebound
Wall Street finished mostly higher Thursday as stocks recovered from an early pullback, helped by a retreat in Treasury yields and gains in semiconductor shares.
The Dow Jones Industrial Average edged up 21 points, or less than 0.1%, to 50,926, while the S&P 500 added 15 points, or 0.2%, to 7,666. The Nasdaq was little changed, rising 11 points to 26,872.
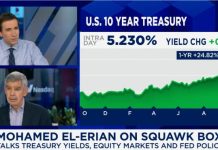
The rebound came after long-term Treasury yields pushed to their highest levels in decades earlier in the session. The 10-year yield flirted with 5.3%, while the 30-year topped 5.6%, as investors continued to weigh sticky inflation and expectations for a higher long-term neutral rate from the Federal Reserve.
Tech stocks provided some support, with chipmakers leading the move higher after Micron’s strong results. Micron shares recovered from earlier losses to finish about 3% higher.
Attention now turns to Nike, which is due to report quarterly results after the closing bell.
3:30pm: Small cap wrap
- Sintana Energy Inc (TSX-V:SEI, OTCQB:SEUSF, FRA:3ZX1, AIM:SEI) said its 49%-owned affiliate Trago Energy has agreed to sell its 10% interest in Namibia’s PEL 90 offshore licence to a Chevron affiliate for $11 million in cash plus contingent payments tied to appraisal and production milestones.
- Nine Mile Metals Ltd. (CSE:NINE, OTCID:VMSXF, FRA:KQ9) said a second drill rig has arrived at the Tribag-West Wedge target in New Brunswick, with drilling expected to begin soon as part of its 10,000-metre 2026 program.
- Sigma Lithium Corp (TSX-V:SGML, NASDAQ:SGML, ASX:SAU) maintained its fiscal 2027 guidance of 330,000 tonnes of lithium concentrate despite temporarily suspending Brazilian operations and delaying its 240,000-tonne 12-month guidance by three months.
- Snail Inc (NASDAQ:SNAL) is discounting games across its portfolio during the October 1 to 8 Steam Autumn Sale, highlighting its horror titles to attract a wider audience.
- M2i Global Inc (OTC:MTWO) expanded its partnership with Regenerate Technology Global to bring battery recycling and data intelligence technology to customer plants worldwide, including facilities under development.
- Standard Uranium Ltd (TSX-V:STND, OTCQB:STTDF, FRA:9SU0) completed its largest drill program at the Davidson River project in Saskatchewan, drilling 6,734 metres across 12 holes and recording the highest radioactivity seen on the property to date.
- Miivo AI (TSX-V:MIVO) agreed to acquire Switzerland-based First Five Partners as it expands into European sports technology, adding expertise in fan engagement, audience intelligence and digital transformation.
- Gunnison Copper Corp (TSX:GCU, OTCQB:GCUMF, FRA:3XS0) appointed former Hudbay Minerals chief operating officer Andre Lauzon to its board, bringing more than 30 years of experience in mine development, operations and permitting.
2:30pm: Market movers
- Netflix Inc (NASDAQ:NFLX, XETRA:NFC) said viewership rose 2% in the first half of 2026, with co-CEO Ted Sarandos acknowledging that the streaming giant is not growing as quickly as he would like.
- Nine Mile Metals Ltd. (CSE:NINE, OTCID:VMSXF, FRA:KQ9) said a second drill rig has arrived at the Tribag-West Wedge target at its Wedge VMS Project in New Brunswick, with drilling on seven electromagnetic conductor plates expected to begin soon.
- McCormick & Company Inc (NYSE:MKC) beat third-quarter estimates for adjusted earnings and sales, helped by wider margins and the acquisition of McCormick de Mexico.
- Micron Technology Inc (NASDAQ:MU) reported results above the high end of its outlook and forecast continued quarterly revenue and gross margin growth through fiscal 2027, prompting analysts to raise price targets as high as $1,625.
- Accenture PLC (NYSE:ACN) reported fourth-quarter revenue and adjusted earnings above expectations and forecast fiscal 2027 local-currency revenue growth of 3% to 6%, sending its shares more than 18% higher.
1:15pm: Bond selloff intensifies
The global bond selloff is getting more intense, putting pressure on Wall Street this afternoon, although the S&P has stabilized around the flatline.
“A sharp sell-off in US Treasuries, fuelled by expectations of tighter monetary policy amid persistent inflation and robust economic growth, drives global yields higher at the start of Q4, with US, German and Japanese borrowing costs reaching multi-decade highs ahead fo Friday’s US employment report,” said Axel Rudolph, Chief Technical Analyst at online trading and investing platform IG.
“US jobless claims falling to their lowest level since July, higher construction spending and manufacturing prices put additional pressure on stock markets.”
12:10pm: Google unveils new AI model
Alphabet Inc (NASDAQ:GOOG)‘s Google has unveiled Gemini 4 Argon, its first flagship model release since February, saying the model leads benchmarks in long-horizon coding, finance, legal work and video understanding.
Access is initially limited to select cyber defenders and Google’s internal teams while the company tests safeguards.
Google said broader access will follow, starting with paid API customers and Google AI Ultra subscribers, but gave no public release date. It is also taking part in the Trump administration’s voluntary pre-release model access process before wider availability.
Elsewhere, London stocks closed at four-month lows, with the FTSE 100 losing 1.7% to finish at 10.428 points.
11:15am ET: Micron keeps analysts bullish
Micron Technology Inc (NASDAQ:MU) (Micron Technology Inc (NASDAQ:MU)) shares were down 2% Thursday morning, but analysts responded to the chipmaker’s latest earnings with price targets as high as $1,625, citing deeper pricing visibility and a major capital return program on the horizon.
Micron again reported results above the high end of its outlook and guided its next quarter well above expectations. Management said it sees sequential revenue and gross margin growth every quarter through fiscal 2027.
The company forecast fiscal first-quarter revenue well above expectations on Wednesday, after fourth-quarter revenue surged 379% from a year earlier to $54.23 billion.
10:00 am ET: Tech and AI support
Wall Street’s main indexes opened higher on Thursday, supported by gains in technology and consulting stocks despite inflation concerns and rising government debt pushing Treasury yields to their highest levels since 2002.
Resilient jobless claims also supported sentiment by pointing to continued strength in the US economy.
At 9.30am ET, the Dow Jones Industrial Average rose 91.75p, or 0.1%, to 50,997.80, while the S&P 500 gained 19.39p, or 0.25%, to 7,670.93 and the Nasdaq Composite climbed 120.49p, or 0.46%, to 26,984.50.
US jobless claims fell for fourth straight week as per a report by the US Department of Labor.
US initial jobless claims fell by 1,000 to 197,000 in the week to 26 September, below economists’ expectations of 200,000 and signalling continued resilience in the labour market.
The stronger-than-expected reading could support US stocks by pointing to continued economic activity in trade on Thursday, but it may also reduce expectations for Federal Reserve rate cuts and put further upward pressure on Treasury yields.
With the 10-year Treasury yield already above 5.3%, investors are likely to focus on whether the stronger labour market reinforces expectations that interest rates will remain elevated.
At 9:45 am ET, US Treasury yields continued to rise, keeping pressure on bonds and risk assets, while UK gilt yields edged lower after a sharp recent sell-off.
A resilient labour market supports consumer spending and economic growth, which can underpin corporate earnings.
Despite very strong results and an upbeat outlook, Micron shares fell 1.7% to $1,047.03 at 9:49 am ET.
Nvidia, however, rose 2% to $231.86 in early trade, helping support the technology sector and Nasdaq at the open.
Bitcoin’s late-Wednesday rally following cooler-than-expected US inflation data faded on Thursday as elevated Treasury yields weighed on demand for risk assets.
Bitcoin briefly rose above $85,500 on Wednesday after the August personal consumption expenditures price index showed inflation cooling more than expected.
The cryptocurrency was up 0.4% at just above $83,700 in Asian trading on Thursday, but fell to $83,461 by 9:30am ET, down more than 1%.
The softer inflation data initially supported Bitcoin by reducing expectations of another Federal Reserve rate increase, but rising Treasury yields subsequently reversed much of the gain.
The FTSE 100 has slipped back into a 1% decline, while the FTSE 250 is down 0.7%, with both indices giving up part of their afternoon recovery as bond-market pressure continues to weigh on sentiment.
At 9:50 am ET, FTSE 100 was 107p down at 10,498, while FTSE 250 was down 174p at 24,363.
9:00 am ET: Tech, AI give strength
Closer to Thursday’s opening bell, all three US futures moved into positive territory, reversing the earlier weakness in Dow futures.
The improvement is being supported by strength in technology and AI-related stocks.
At 8:45 am ET, Dow futures had regained territory and were up 191p, or 0.3%, at 51,469.
S&P 500 futures were up 27.25 p, or 0.3%, at 7,742.75, while Nasdaq 100 futures were up 149.50p, or about 0.5%, at 30,848.25.
Global bond markets continue to be under pressure as investors price in a combination of higher inflation, rising government borrowing and potentially higher interest rates.
The latest rise in oil prices linked to US-Iran tensions has added to inflation fears, prompting traders to anticipate further rate increases and pushing government bond yields higher across the US, Europe and Japan.
The underlying concern is that higher debt burdens, increased government borrowing and persistent inflation could require investors to demand greater returns to hold long-term bonds, meaning yields may remain elevated.
Endeavour Mining was the top FTSE 100 riser, gaining 2%, followed by Sage, up 1%, and London Stock Exchange Group, which rose 1%.
Land Securities gained 1%, while Computacenter rose 1%, Rolls-Royce added 1%, Pearson increased 1% and Informa advanced 1%.
Games Workshop was the biggest FTSE 100 faller, down 5%, followed by Lion Finance Group, which fell 4%, and Weir, down 3%.
NatWest fell 3%, HSBC dropped 2% and British American Tobacco declined 2%.
At 1:54 pm BST, the FTSE 100 pared earlier losses to trade down 1%, while the FTSE 250 fell less than 1%, as both indices remained under pressure from the global bond sell-off.
FTSE 100: 10,540.67, down 65p, or 0.62%
FTSE 250: 24,446.26, down 93p, or 0.38%
Best of the brokers
Citi & Deutsche Bank: BAT (British American Tobacco PLC (LSE:BATS)) ‘buy’ maintained, £52 target; capital markets day boosted confidence in medium‑term growth delivery
Panmure Liberum: Greggs (Greggs PLC (LSE:GRG)) upgraded to ‘buy’ from ‘hold’, target raised to 2,440p from 1,560p after stronger Q3 sales and profit forecast upgrades
Deutsche Bank: Greggs target lifted.
UBS & Jefferies: Reckitt (Reckitt Benckiser Group PLC (LSE:RKT, OTCQX:RBGLY)) both ‘buy’ maintained; UBS sees Q3 group LFL +3.7%, Core Reckitt +4.2%, Jefferies more cautious near‑term but supportive longer‑term
Panmure Liberum & Cavendish: Future (Future PLC (LSE:FUTR)) ‘buy’ maintained after £30m buyback paused; brokers back debt reduction focus
Cavendish: Filtronic (Filtronic PLC (LSE:FTC)) ‘buy’ reiterated, 290p target; shares +14% to 270p after record $68.1m SpaceX order
1:00 pm BST: Risk appetite hit
The global bond sell-off continues on Thursday, with government borrowing costs rising across major markets and putting further pressure on equities.
France’s 10-year government bond yield rose 10 basis points to 4.96%, while the UK’s 30-year gilt yield climbed above 6%, its highest level since 1998.
A benchmark for global borrowing costs and asset prices, the 10-year US Treasury yield touched its highest level since 2002.
Traders now expect at least three further Federal Reserve rate increases before mid-2027, adding to pressure on borrowing costs and equities, reports Reuters.
At 12:45 pm BST, US futures are mixed, with Nasdaq 100 futures higher while Dow futures are lower. Technology was providing support.
Nasdaq 100 futures: 30,889.50, up 191p or 0.6%
S&P 500 futures: 7,737, up 22p
Dow futures: 51,252, down 26p, or 0.05%
Stocks that will be in focus when Wall Street opens later today are Micron, which reported a strong fiscal fourth-quarter result; Alphabet, after Google unveiled its new Gemini 4 Argon AI model; Constellation Energy, which agreed to a $3 billion, 20-year deal with Amazon to expand a Maryland nuclear plant; and Hewlett Packard Enterprise, which snagged a large order involving AMD’s Helios AI systems.
European markets also fell sharply, with the STOXX 600 down over 1% and at its lowest level since June, as higher bond yields and inflation concerns weighed on investor sentiment.
The rise in yields has increased financing costs for companies and mortgage borrowers, while putting further pressure on heavily indebted governments.
The bond sell-off was also spreading into other asset classes, with European banking stocks falling as much as 3%, while an index of credit default swaps on junk-rated companies reached its highest level since early April, signalling rising concern over credit risk.
Rising borrowing costs and inflation concerns also continue to weigh on equities.
Ireland’s annual inflation rate rose to 3.9% in August, its highest level in three years, according to flash data from the Central Statistics Office.
The increase from 3.4% in July was driven by a 2.9% monthly rise in energy prices, the harmonised index of consumer prices showed.
The US dollar showed modest strength against both the euro and sterling, with the dollar/euro rate rising 0.32% to €0.8855 and the dollar/sterling rate gaining 0.31% to £0.7561, while sterling traded at $1.32.
Brent crude futures were up over 2% to $100.62 a barrel on Thursday at 12:30 pm BST as renewed uncertainty over US-Iran negotiations and supply disruptions through the Strait of Hormuz increased concerns over global oil supplies.
In post noon trade, the FTSE 100 fell 112.78p, or 1.06%, to 10,493.22, while the FTSE 250 dropped 184p, or 0.7%, to 24,355.41.
12 noon BST: Investors cautious
Growing investor caution continues to negatively impact UK equities, with gains for energy companies from higher oil prices being overshadowed by rising government bond yields. Persistently high crude prices and higher financing costs could increasingly weigh on the UK housing market and consumer spending.
The FTSE 100 fell to a three-month low on Thursday at 11:08 am BST (10:08 am GMT) as rising global bond yields fuelled inflation concerns and weighed on investor sentiment. The blue-chip index fell 1.48% to 10,448.78 putting it on course for a fourth consecutive session of losses, while the FTSE 250 fell 1.23%, reports Reuters.
At noon, the FTSE 100 remained under pressure, falling 133p, or over 1%, to 10,472.53, while the FTSE 250 fell 258p, or 1.05%, to 24,282.06.
Other European markets are following the London trend and are down too.
US futures point to a mixed Wall Street open, with Nasdaq 100 futures up 176p, or 0.5%, S&P 500 futures up 15p, while Dow futures is down 63p, or 0.1% at 51,213, at 6:35 am ET as strong technology earnings provide some support amid rising Treasury yields and inflation concerns.
Reuters reported Dow futures fell to over a three-month low on Thursday.
This comes as US Treasury yields climbed to multi-year highs, adding pressure to equities by raising borrowing costs and reducing the appeal of riskier assets.
Investors will also be watching the latest US jobless claims data on Thursday.
11:00 am BST: London stocks retreat
A global bond sell-off has pushed UK 30-year gilt yields above 6% for the first time since 1998, as rising borrowing costs and inflation concerns weigh on equities, with the FTSE 100 down 157p, or over 1%, to 10,448.
Even the more domestically focused FTSE 250 has come under pressure from rising UK borrowing costs and inflation concerns, falling 308p, or over 1% to 24,231.
The US 10-year Treasury yield has hit its highest level in 24 years as the global bond sell-off gathers pace.
Meanwhile, Filtronic shares rose over 4% to 247.5p after the UK designer and manufacturer of advanced radio-frequency technology secured a $68.1 million follow-on order from SpaceX, its largest contract from the satellite company to date. Proactive Investors
The order, for Cerus E-band gallium nitride solid-state power amplifiers, is expected to be largely fulfilled in the 2028 financial year, providing greater visibility over future revenue. pluang.com
Small-cap round-up
IXICO PLC (LSE:IXI, OTC:PHYOF, FRA:PYPB), the neuroscience imaging company, has presented research at a European conference showing one MRI technique provides better contrast than another when imaging a brain region linked to Parkinson’s disease.
ATOME PLC (AIM:ATOM), the AIM-listed developer of the Villeta project in Paraguay, has given notice to terminate its 2022 power purchase agreement with ANDE at the end of 2026 after failing to agree on a proposed standstill.
Topps Tiles PLC (LSE:TPT), the UK tile specialist, expects full-year adjusted profit before tax to meet market expectations despite challenging trading and a 1.3% decline in revenue to about £292 million.
Pantheon Resources PLC (AIM:PANR, OTCQX:PTHRF) has appointed Alaska energy veteran David Wilkins as chief executive with immediate effect, as it advances its Kodiak and Ahpun projects and farm-out discussions.
Filtronic PLC (LSE:FTC), the UK designer and manufacturer of radio-frequency technology, has secured a $68.1 million follow-on order from SpaceX, its largest contract with the satellite company.
10.00 am BST: Manufacturing data adds to inflation concerns
UK manufacturing output growth slowed to a six-month low in September, while input-cost inflation accelerated for the first time in four months, according to the survey released at 9.30am.
The figures added to concerns that weak growth and persistent inflation could keep interest rates elevated, with the UK 30-year gilt yield reaching 6%.
The FTSE 100 extended its decline to 1.8%, or 189 points, at 10,417, while the FTSE 250 fell 1.4% to 24,190.
Games Workshop was the biggest blue-chip faller, down 5%, although no fresh company announcement appeared to explain the move.
Banks suffered heavily, with Lion Finance down 4.2%, HSBC losing 3.8%, NatWest falling 3.7% and Standard Chartered declining 3.6%.
Construction-related shares also weakened, with Breedon down 5.2%, Wickes losing 4.4% and Berkeley Group falling 3.9%.
Rolls-Royce led just four FTSE 100 risers with a 0.6% gain, while the pan-European Stoxx 600 fell 1.2%.
9.00am BST: London sell-off gathers pace
The FTSE 100 dropped 1.7%, or 183 points, to 10,423, while the FTSE 250 lost 1.4% as rising global borrowing costs triggered a broad European sell-off.
London underperformed its continental peers, with the pan-European Stoxx 600 and Germany’s DAX both down 0.5%, while France’s CAC 40 and Spain’s IBEX 35 fell 0.8% and Italy’s FTSE MIB declined 0.5%.
The US 10-year Treasury yield reached 5.33%, its highest since 2002, while the UK’s 30-year gilt yield approached 6%.
Games Workshop fell 5.8%, British American Tobacco lost 3.6% and HSBC declined 3.1%, while Breedon, Vistry and Travis Perkins (LSE:TPK) led the mid-cap fallers.
Rolls-Royce topped the limited blue-chip risers with a 1% gain, while Volex led the FTSE 250 with a 1.1% advance.
8.15am BST: London opens sharply lower
The FTSE 100 fell 1.1%, or 120 points, to 10,486, while the FTSE 250 declined 0.9% to 24,314 as rising global bond yields weighed on London shares.
Rolls-Royce led a limited group of blue-chip risers with a 1.9% gain, followed by Polar Capital Technology Trust at 1.1%.
Precious-metals miners Fresnillo and Endeavour Mining advanced as gold traded above US$4,200 an ounce.
Among mid-caps, XPS Pensions climbed 4.8%, AO World gained 4.7%, Ferrexpo rose 2.8% and Raspberry Pi added 2.7%.
Attention now turns to the final UK manufacturing purchasing managers’ index for September.
7.00am BST: London faces softer start to fourth quarter
The FTSE 100 is expected to open lower on Thursday as rising global borrowing costs overshadowed gains among technology shares in Asia and the United States.
December futures fell 45 points, or 0.4%, to 10,615.5 before the open after the blue-chip index closed 31 points lower at 10,606 on Wednesday.
London’s benchmark lost about 2% during September, marking its weakest month since March as higher oil prices and bond yields increased concerns about inflation and interest rates.
Wall Street ended mixed overnight, with the S&P 500 falling 0.3% and the Dow Jones Industrial Average losing 0.9%, while technology strength helped the Nasdaq Composite gain 0.2%.
The US 10-year Treasury yield reached 5.3%, its highest level since 2002, after stronger economic data outweighed a softer-than-expected inflation reading.
Asian markets were divided, with Japan’s Nikkei 225 jumping more than 3% as semiconductor shares rallied, while the broader Asia-Pacific market outside Japan slipped 0.2% and mainland Chinese markets remained closed for a holiday.
The ASX 200 closed at 8,622.10, down 1.90% or 167.20 points.
Brent crude fell 1.4% to US$96.64 a barrel and West Texas Intermediate dropped 1.7% to US$88.85 as concerns about Middle Eastern supplies continued to ease.
Gold gained 0.8% to US$4,219 an ounce, silver advanced 1.9% to US$61.72 and copper edged 0.2% higher.
Meanwhile, Bitcoin remains at about US$83,500, edging 0.2% higher over the past 24 hours.
The final UK manufacturing purchasing managers’ index for September is due at 9.30am, while tile retailer Topps Tiles is scheduled to issue a full-year trading upda