4:20pm: Bruising week
Wall Street ended mixed on Friday, with the Nasdaq and S&P 500 recovering some ground after a bruising week for technology stocks, while the Dow slipped.
The Dow Jones Industrial Average fell 237 points, or 0.5%, to 51,286, while the S&P 500 added 23 points, or 0.3%, to 7,377. The Nasdaq Composite led the rebound, climbing 264 points, or 1.1%, to 24,579.
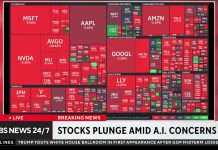
The modest recovery followed a technology sell-off that wiped more than $2.5 trillion from global market value, as investors reassessed the cost and potential returns of heavy investment in artificial intelligence. Bargain hunters stepped in on Friday, helping large-cap technology shares claw back some of their recent losses, although the sector remained under pressure heading into the weekend.
Economic data also gave investors something to think about. Stronger-than-expected private-sector job growth, a 3.6% annualised increase in third-quarter productivity and weekly jobless claims near multi-decade lows pointed to a resilient US economy.
While that is generally good news for growth, it complicates the Federal Reserve’s next move. The strength of the data has fuelled speculation that policymakers could consider another interest rate increase in December, rather than resuming cuts.
Attention now turns to another busy week of corporate earnings, with Constellation Energy, Barrick Mining, CoreWeave, Cisco Systems and Applied Materials among the companies due to report.
3:40pm: Small cap wrap
- Purepoint Uranium Group Inc (TSX-V:PTU, OTCQX:PTUUF, FRA:P5X0) outlined the disconnect between rising uranium prices and falling uranium stocks, with CEO Chris Frostad arguing that stronger long-term contracting and supply concerns have yet to translate into investor confidence.
- Custom Health Holdings Inc (TSX:CHLT) filed a final short-form base shelf prospectus that would allow the Canadian healthcare company to raise up to $200 million.
- Alvopetro Energy Ltd (TSX-V:ALV, OTC:ALVOF, FRA:A6Y0) reported a 36% year-over-year increase in third-quarter funds flow from operations to $14.3 million, supported by higher revenue, stronger production and realized prices, while its latest Brazil drilling encountered nearly 97 metres of potential pay.
- Novo Resources Corp (TSX:NVO, OTCQX:NSRPF, ASX:NVO, FRA:1NOR) outlined plans for a 2,700-metre reverse circulation drilling program at its Tibooburra Gold Project in New South Wales, targeting extensions to high-grade mineralization at the Clone prospect.
2:30pm: Market movers
- Hims & Hers Health rose 5% after the telehealth provider announced an agreement with Eli Lilly to expand access to its FDA-approved obesity drugs Foundayo and Zepbound.
- DraftKings fell 28% after missing third-quarter revenue expectations and issuing a weaker-than-expected full-year outlook as it steps up investment in prediction markets.
- Firefly Aerospace jumped 23% after securing a $1.3 billion agreement to supply propulsion systems for AST SpaceMobile’s planned Blacklift heavy-lift rocket.
- Oklo gained 19% after the nuclear reactor developer reported a narrower-than-expected third-quarter loss and revenue above analyst estimates.
- Moderna rose 7% after beating third-quarter earnings and revenue expectations and raising its full-year sales growth outlook.
- Atlassian (NASDAQ:TEAM) fell nearly 12% despite beating first-quarter fiscal 2027 estimates, as its full-year revenue outlook pointed to slowing growth.
- Cloudflare climbed 20% after third-quarter revenue and adjusted earnings beat expectations and its sales outlook exceeded analyst forecasts.
- Airbnb gained 14% after beating third-quarter revenue and earnings estimates, recording its fastest revenue growth in more than three years and raising its full-year outlook.
1:30pm: Strong hiring shifts Fed outlook
US job growth accelerated sharply in October, with nonfarm payrolls rising by 165,000, well above expectations of 65,000, while the unemployment rate edged down to 4.1%. Average hourly earnings increased 0.4% month over month, pushing annual wage growth to 3.1%.
Bank of America analysts said the report was “hawkish all the way,” adding that it “should ease some jitters and clear the way for a Dec hike.” They said stronger employment and wage data make arguments for a pause less compelling, leaving the Federal Reserve more focused on inflation and potentially bringing another rate hike into view.
12:15pm: Checking in on markets
A quick check in at where the UK and US markets stand after a volatile week.
London’s FTSE 100 index had a rough day, finishing 1% lower at 10,674 points. That amounts to about 0.5% lower on the week.
US markets were faring slightly better by the midday point of trading on Wall Street, but not coming close to recovering yesterday’s losses.
The Dow was down about 0.2%, the S&P 500 heading 0.4% higher and the Nasdaq performing more strongly with a 0.9% gain from opening levels.
Still, the tech-heavy Nasdaq was on track to lose over 4% on the week as fears of an AI-driven selloff persist.
11:15am: Jobs growth beats forecasts
US nonfarm payrolls increased by 165,000 in October, well ahead of economists’ expectations for a gain of 65,000, while the unemployment rate edged down to 4.1% from 4.2%.
Private-sector payrolls rose by 159,000, compared with forecasts for 64,000, while government employment increased by 6,000 after falling by 17,000 in the previous month.
Average hourly earnings rose 3.1% year over year, above expectations for 2.9%, while the labour force participation rate ticked up to 61.9% from 61.8%. The average workweek was unchanged at 34.4 hours.
Chris Zaccarelli, chief investment officer at Northlight Asset Management, said the figures point to an economy that remains resilient despite higher oil prices and interest rates.
He noted that economic growth is running at 3.4% and corporate earnings are up more than 25% year over year, adding that the unemployment rate of 4.1% is at or close to levels consistent with full employment.
While acknowledging that there are limits to how high interest rates can rise before economic strains emerge, Zaccarelli said investors should look beyond short-term market reactions to shifting economic narratives and focus on longer-term fundamentals.
2:30 GMT: Market Movers
Major indices showed a mixed performance during the Wall Street Opening as tech stocks staged a rebound following a severe broad-market sell-off the prior day. Before the opening bell, the fund tracking the Nasdaq-100 was up 1.4%, the S&P 500 tracker edged up 0.1%, while the Dow Jones tracker lagged, down 0.9%.
1:00 GMT / 08:00 EST: The Handover & Wall Street Preview
Global equity markets are experiencing severe cross-currents today as the baton passes from Europe to New York.
European markets have been hammered by a major global technology sell-off triggered by the U.S. midterm election outcomes, which have renewed regulatory anxieties surrounding artificial intelligence and data center development.
As Wall Street prepares to open, equity futures are attempting to establish a tentative floor after yesterday’s punishing drop.
While contracts tracking the tech-heavy NASDAQ Composite (INDEXNASDAQ:.IXIC) and S&P 500 (INDEXSP:.INX) show a slight positive bounce as dip-buyers probe tech names, sentiment remains extremely fragile ahead of the looming October jobs report.
Meanwhile, Dow Jones Industrial Average (INDEXDJX:.DJI) futures remain pinned deep in negative territory.
Across the Atlantic, London’s blue-chip index has taken a significant hit, compounded by domestic factors including house prices recording their sharpest annual contraction in three years alongside hawkish caution from the Bank of England.
FTSE 100 Level: 10,566.29 (-1.91%)
12:00 pm GMT: London blue chips record heavy losses
The INDEXFTSE:UKX (FTSE 100) fell 2% to 10,542 points at midday as a dramatic global equity retreat hit London stock markets.
The FTSE 250 index dropped 1% to 24,396 points while the broader AIM All-Share index lost 1%.
Investors dumped equities globally following a heavy overnight decline on Wall Street, where the technology sector entered correction territory.
The sell-off followed a sweeping victory for the Democratic party in the United States midterm elections, which sparked fears of tighter restrictions on artificial intelligence investments.
Large commodity companies led the declines in London, with the FTSE 100 mining giant Antofagasta PLC (LSE:ANTO) dropping 3%.
Glencore PLC (LSE:GLEN, ASX:GLC), the Swiss commodity trading and mining company, also shed 3% of its share value during morning trading.
Energy majors felt the pressure as well, with Shell PLC (LSE:SHEL, NYSE:SHEL) losing 2% amid falling oil prices.
Its blue-chip rival BP (LON:BP) matched that decline with a 2% drop.
In the mid-cap index, the investment manager Man Group PLC (LSE:EMG) plunged 5% after analysts at Deutsche Bank lowered their price target for the stock.
European markets mirrored the London rout, with the Dax index in Frankfurt losing 2% and the Cac 40 index in Paris down 1%.
11:00 am GMT: London stocks extend losses
The FTSE 100’s losses on Friday have widened.
The footsie was down 206p on the day, while the FTSE 250 had fallen 283p at about 10:48 am GMT as selling pressure intensified across the UK marke
Globally, investors are turning to the safety of government bonds on Friday as global stock markets extended their losses.
US Treasury yields are falling on Friday as investors seek safety amid the global equity sell-off, while UK 10-year gilt yields have edged higher to 5.146%.
The 10-year yield has fallen by 6 basis points to 4.84%, indicating increased demand for US government bonds.
The 10-year-UK gilt yields has also edged up by 0.8 basis points to 5.146%.
The US dollar is gaining ground against both the pound and the euro on Friday, with the latest currency snapshot showing broad-based dollar strength.
The USD strengthened against sterling and the euro, rising 0.47% against the pound to 0.7469 and 0.40% against the euro to 0.8949, as investors sought safety amid the global stock market sell-off.
Small-cap round up
Strategic Minerals (AIM: SML) said it has completed more than 7,500 metres of drilling at its Redmoor tungsten-copper-tin project in Cornwall, bringing it closer to an updated resource estimate while identifying mineralisation beyond the existing geological model.
Its wholly owned subsidiary, Cornwall Resources, has completed 13 holes, comprising 11 of the planned 42 infill holes and two metallurgical holes, with all intersecting the targeted sheeted vein system.
The drilling programme remains on schedule and within budget.
10:00 am GMT: FTSE 100 continues in red
London’s stock market was firmly in negative territory.
The FTSE 100 and FTSE 350 were among the weakest, while the more domestically focused FTSE 250 and AIM All-Share proved relatively resilient.
At 9:53 am GMT, the FTSE 100 was down 136p, or 1.27%, to 10,646.17, while the FTSE 350 and FTSE All-Share both lost 1.18%.
The domestically focused FTSE 250 proved more resilient, declining about 125p, or 0.51%, while the FTSE AIM All-Share slipped 0.36%, as selling pressure remained concentrated among larger listed companies.
Major technology and information-services stocks have also weakened, consistent with the global technology-led sell-off.
Sage fell 3.12% and RELX lost 2.76%, adding to pressure on growth-oriented and information-services companies.
Mining and materials stocks are, however, showing relative strength.
Despite wider market weakness, interest in metals and mining shares seem fixed with Metlen, Endeavour Mining, Fresnillo and Weir being among the strongest performers.
British Airways owner International Consolidated Airlines Group (IAG) has cut its capacity and investment forecasts again, as it reduces routes and prioritises profitability in response to soaring fuel costs.
But airline shares led by IAG gained over 2%, making it one of the leading blue-chip risers.
Telecoms and advertising sectors are also under selling pressure.
Airtel Africa and BT Group are the two biggest fallers, while WPP lost 3.08%, pointing to weakness in telecoms and advertising-related stocks.
Defensive consumer and healthcare stocks are also down.
Imperial Brands, British American Tobacco, AstraZeneca and Reckitt all declined, showing that selling was not restricted to technology or cyclical shares.
UK retail footfall fell 4.7% year on year in October, worsening from a 2.9% decline in September, as weak consumer confidence and stormy weather hit high streets, according to the British Retail Consortium.
High street footfall dropped 5.2%, while retail parks saw a 3.6% decline and shopping centres a 4.1% fall.
9:00 am GMT: Footsie in red
London and other European stocks fell sharply on Friday, tracking a global sell-off in technology shares as concerns over artificial intelligence (AI) investment and the prospect of tighter US regulation weighed on investor sentiment.
The FTSE 100 dropped 1.34% to 10,638.02, while Germany’s DAX fell 1.33% and France’s CAC 40 lost 1.01%, with the pan-European Stoxx 600 down 1.18%, according to data available at 8.43am GMT.
The declines followed heavy losses on Wall Street and in Asian markets, as investors grew increasingly concerned about the returns on massive AI investments and the potential for political pressure to slow data-centre expansion.
Reuters reports that the global oil market is showing signs of returning to a supply surplus as high prices curb demand, despite the unresolved Iran war disrupting Middle Eastern exports since March, according to analysts and traders.
On Friday, at about 8:55 am GMT, Brent crude futures for January 2027 were down at $97.93 a barrel, down 36 cents, or 0.37%, in the latest trading session, keeping prices below the $100 threshold.
The US dollar is broadly stronger against major currencies on Friday morning, with the biggest gains against the Australian dollar, sterling and the euro as investors seek safety amid the global technology sell-off, with US jobs data now in focus.
8:15 am GMT: FTSE 100 falls
The FTSE 100 opened at 10,784.16 on Friday, marginally above Thursday’s closing level of 10,782.66, a gain of 1.50p, or 0.01%.
At 8:15 am GMT, the index then fell to 10,623.75.
Coca-Cola HBC shares led the gainers, rising 1.28% to 4,104p, followed by Metlen Energy & Metals, up 0.54% to €44.80. Scottish Mortgage Investment Trust gained 0.52% to 1,441.5p, while Pershing Square Holdings (LSE:PSH) rose 0.26% to 3,860p.
UK house prices fell 0.6% in October to an average £296,285, taking the annual decline to 1.2%, the biggest since October 2023, according to the Lloyds House Price Index.
Prices were 0.5% lower in the three months to October.
Asian stock markets, too, tumbled on Friday, led by sharp losses in Japan and South Korea, as investors sold technology shares amid mounting concerns about the cost and returns of artificial intelligence (AI) investment following the US midterm elections.
This followed Wall Street’s steepest single-day decline in more than a year on Thursday.
6:30 am GMT: FTSE 100 set to slide
The FTSE 100 is set for a sharp fall on Friday, with IG pointing to around 10,689, down roughly 1%, after a technology-led rout on Wall Street that spread across Asian markets.
The Nasdaq plunged 5.5%, the S&P 500 fell 4.4%, and the Dow dropped 3.4% as investors dumped AI and semiconductor stocks.
Japan’s Nikkei closed 6.2% lower at 57,267, while South Korea’s KOSPI fell more than 5% after an earlier plunge triggered a circuit breaker.
Australia’s ASX 200 proved more resilient, closing 0.5% lower at 9,021, while Hong Kong was also in negative territory.
Brent crude rebounded towards $100 a barrel, while gold slipped towards US$4,050.
Bitcoin has fallen back toward $76,000 as a sharp sell-off in US technology stocks spilled into cryptocurrency markets, triggering more than US$1 billion in leveraged liquidations.
UK investors are also digesting Thursday’s Bank of England rate increase to 4%.